GameStop’s (NYSE: GME) Q2 2026 results offer intriguing details suggesting it may be time to take the stock seriously. Maybe. The critical details lie within the Collectibles segment, which has long been the company’s growth focus. It grew 57% year over year to 45.1% of sales and is expected to continue growing. It also contributed to the company’s profitability, but it may not be enough to keep the market in gear.
As good as the news is, Collectibles are still less than 50% of the business; the remaining segments are in sharp contraction, and there aren’t many other reasons to want to own the stock. Collectibles are unlikely to ever eclipse the strong games and hardware business, raising the question of what you're really getting. As it stands, the company increasingly looks like a collectibles retailer, a cash-rich holding company, and an eBay (NASDAQ: EBAY) investor, while eBay remains by far the cleaner operating business. eBay is growing, producing steadier profits, and, more importantly, generating cash in a way that supports capital returns.
GameStop Rises After Better-Than-Expected Results
GameStop issued an arguably better-than-expected Q2 report, but there isn’t much strength to be seen. The company’s $790.2 million in revenue is slightly above consensus but down nearly 20% from last year, hurt by lapping last year’s console launches, store closures, and its exit from the business in France. Segmentally, Collectibles was strongest, offset by a 47% contraction in Software and a 32% decline in Hardware and Accessories, which are not expected to end.
Software and hardware sales are impaired for numerous reasons, including consumer headwinds and AI. AI and the cloud aren’t expected to replace console-based gaming, but they are changing the environment, primarily through cost. High demand for DRAM and memory is pushing console prices through the roof, leading owners to hold on to older models longer, potentially forever. Games shifting to the cloud raises the longevity question: cloud-based games can disappear, but a disc you own lasts forever (more or less).
Profitability is a factor that investors should note. Not only is the core business generating profits, but its substantial holding in eBay and cash also drive results. The takeaway is that GameStop has potential, but the strategy remains murky, and risks abound. Profitability and collectibles strength are likely to be spotty. Looking ahead, investors can expect GameStop’s core business to continue floundering, collectibles to offset that weakness, and eBay to continue driving value for investors.
Analysts and Institutions Say eBay Is a Better Choice
GameStop’s analyst and institutional activity suggest an improvement is underway, but show little confidence. MarketBeat tracks a single analyst with a current rating, but it is a fresh rating pegged at Hold, up from last year’s Sell. The bad news is that no price target is given, providing no market impetus, while institutional holdings remain small at about 30%, and short interest remains high at just over 13%.
Conversely, 34 analysts rate eBay as a consensus of Hold, providing stronger conviction in the investment. The data shows a 45% Buy-side bias, with some upside to the consensus target, providing a more favorable risk-to-reward scenario. Critical details include steady coverage, firming sentiment, and an uptrend in price target revisions, with recent targets pushing the high end of the range higher. Consensus as of early September suggests about 12% upside for eBay stock, while the high end of $145 amounts to just over 30% upside.
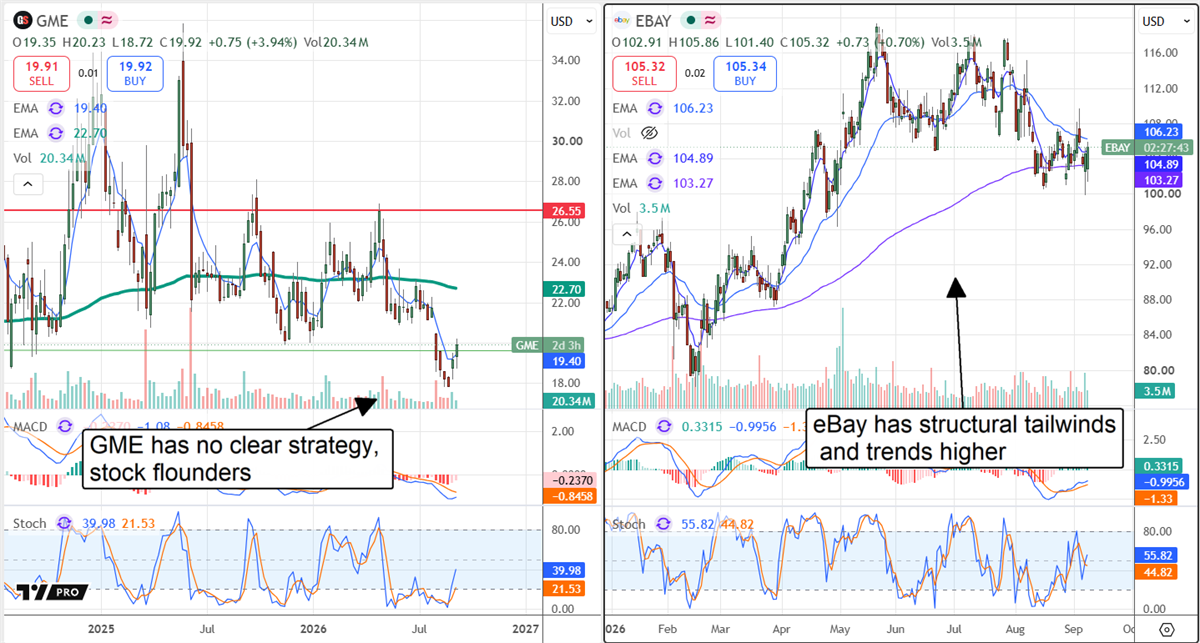
eBay Has Structural Tailwinds, GameStop Does Not
Looking ahead, eBay’s analyst trends are likely to continue, as the company is forecasted to sustain mid-single-digit revenue growth while widening margins. Its catalysts include a sharper focus on key categories, including collectibles and luxury authentication, alongside a lean into AI. AI is helping internally and, more importantly, consumers, with improved listing tools and better consumer engagement showing up in sales and profits.
From a technical standpoint, eBay also looks stronger, with its share price holding up better while GME remains vulnerable to another leg lower. The earnings-driven rebound may lead to a fuller recovery, but hurdles remain. The fall to fresh lows posted in late summer is suggestive, pointing to a market losing confidence and on track to hit lower prices. The only cushion investors have is the cash pile, which accounts for most of the stock’s value.
What the bulls get wrong about GME is that it is no longer a meme stock with potential for explosive short-covering rallies. While short interest remains high, it is well off the astronomical levels seen during the height of the meme frenzy. The bears get it right that core operations are unreliable, hardware and software sales will not rejuvenate the business, and collectibles are unlikely to replace them. In this scenario, strategic focus and execution are crucial, and both are severely lacking.
The article "GameStop’s Comeback Case Is Getting Interesting, But eBay Still Looks Stronger" first appeared on MarketBeat.