MongoDB’s (NASDAQ: MDB) early-September price pullback is a buy-the-dip event, triggered by sell-the-news profit-taking. The key takeaway from the company's Q2 fiscal year (FY2027) earnings report is that the business is accelerating under the influence of AI. AI aids not only internals but also offerings, which are resonating with clients, driving contract wins and services penetration. Key details in the report include the factors that triggered the sell-off and its mitigating factor: jaw-dropping outperformance and profitability.
If one cause for selling stands out, it is the 12% increase in operating expenses. The increase is less unexpected than unwanted, as it cuts into cash flow and capacity to improve shareholder value, but it aligns with capacity expansion to meet demand, which ultimately improves shareholder value.
The mitigating factor, however, is the margin, which expanded significantly due to increased revenue leverage and operational quality, outpacing consensus estimates even with the increased spend. The likely outcome is that this market quickly realizes the value presented, closes the gap formed in early post-release trading, and then moves up to set a fresh high.
MongoDB Isn’t the First to Reveal SaaS-Pocalypse Fears Were Misplaced
MongoDB isn’t the first to reveal that the SaaS-pocalypse fears were overblown, but it is a critical link in the software ecosystem, highlighting systemic and accelerating growth for AI-capable winners. Revenue grew by 30.5% in Q2 FY2027, accelerating sequentially and year-over-year (YOY) to outpace the consensus by more than 500 basis points. Strength came from a 31% increase in Subscriptions, the core segment, supported by a 30% increase in Services.
Atlas, the company’s unified platform for launching, managing, and automating database and database-related workflows, is the primary catalyst. It grew 29%, driven by strength across geographic regions. Enterprise Advanced was also solid, segmentally, growing 36% YOY to 24% of revenue.
Margin news is good, including the impact of spending, which points to increased revenue and improved margins in future quarters. As it stands, adjusted operating margin improved by 900 basis points to 24%, nearly doubling the adjusted net income and free cash flow in the process. Free cash flow of $137.6 enables value gains alongside investment, while adjusted earnings per share (EPS) rose 90% to $1.90 and outperformed by 1800 bps.
Looking ahead, management expects revenue growth to slow but issued a solid forecast, expecting Q2 strength to persist and Q3 to outperform analysts' expectations. Reasons to believe results will fall at the high end of the range or better include the current remaining performance obligation (RPO) and total RPO, which foreshadow acceleration, with current RPO up 73% in the quarter and total RPO up 91%.
Analysts Respond With Vigor! MDB Can Hit Multiyear Highs
The analyst response is vigorous and bullish. MarketBeat tracked eight revisions within the first 12 hours of the report, with all affirming a consensus or higher price point. Two revisions included price target declines, but even they align with the consensus: a solid Moderate Buy with about 25% upside potential relative to the post-release sell-off. Most targets, however, were lifted, including a new high of $560 and several above $500. They suggest not only a return to multiyear highs but the potential to retest all-time highs and move even higher. Assuming the subsequent releases are equally solid, analysts' trends will likely strengthen and reinforce the outlook for significant price gains.
Institutions will be the deciding factor, and the data suggests the downside is limited. The group owns nearly 90% of the stock and has been aggressively accumulating in 2026. MarketBeat data reflects an approximately $4-to-$1 trailing 12-month balance as of mid-Q3, with a sizeable stake taken by California’s Teachers’ Retirement System. It made a notable purchase earlier this year, lifting its stake into the high double digits and reflecting strong conviction in the outlook. With this in play, given the results, the group is more likely to buy into the sell-off than lean into selling, and evidence of buying already exists.
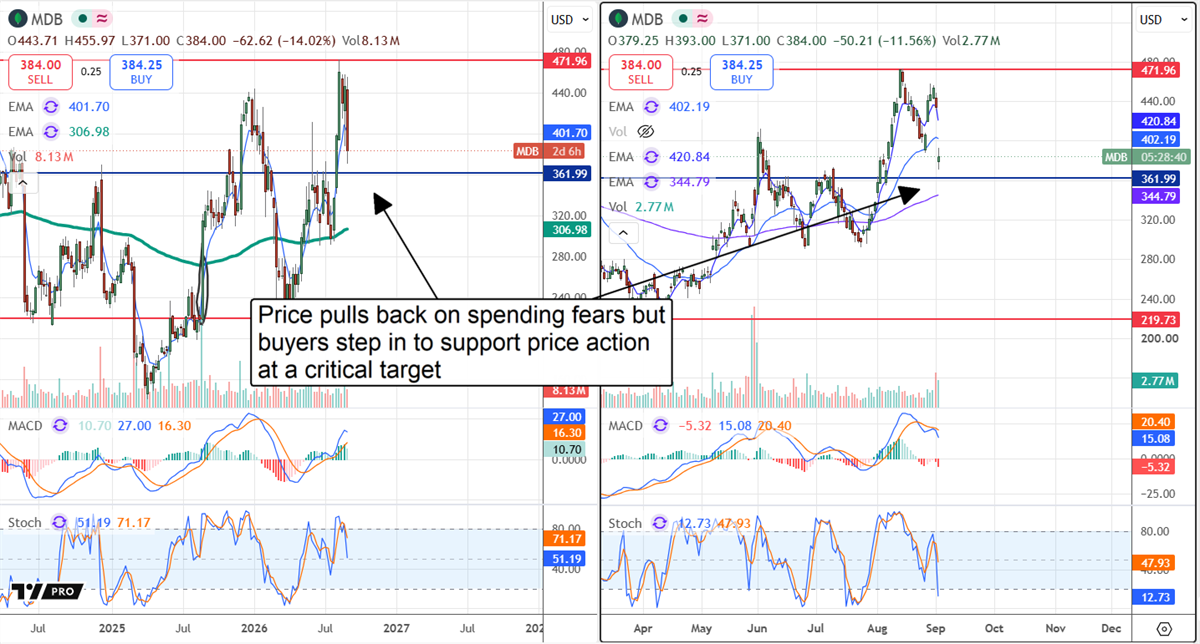
Price action plunged in early trading but did not move lower, signaling buyers at the low, then traded sideways in a sign of indecision. The near-term risk is that selling intensifies, but the more likely outcome is that support holds in the $375 region, support is reestablished, and a price recovery begins over the subsequent few quarters. The bigger risk is the valuation, which prices in a robust growth trajectory. This puts the market in a position for sharp pullbacks and corrections on weakness, regardless of signals that the business has traction and is gaining momentum. Short interest is not a problem right now, and likely won't be anytime soon.
The article "MongoDB’s Spending Fears Collide With a Much Stronger Growth Story" first appeared on MarketBeat.