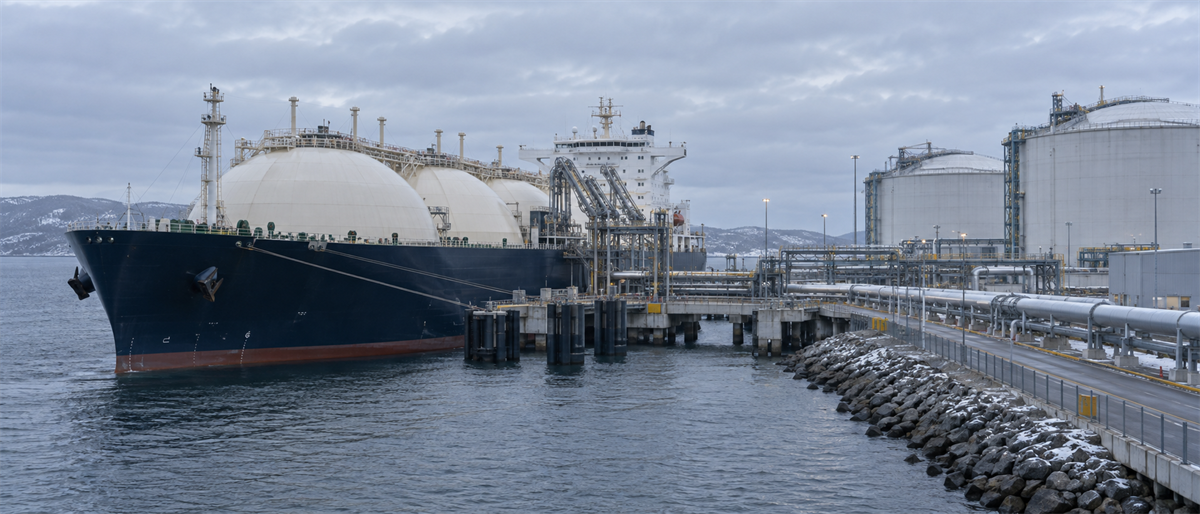
European natural gas inventories entered mid-September at approximately 67% of total capacity, well below the European Union target of 90% before winter. That deficit leaves power utilities and industrial factories vulnerable to sudden price spikes if an early cold front arrives.
Shipping delays and geopolitical tensions around the Strait of Hormuz continue to restrict deliveries from the Persian Gulf, closing off flexible spot relief. As transatlantic price spreads widen, producers with uncommitted pipeline networks and destination-flexible export cargoes are positioned to generate dependable cash flow. Investors tracking the energy sector can look toward three established producers supplying fuel where it is needed most.