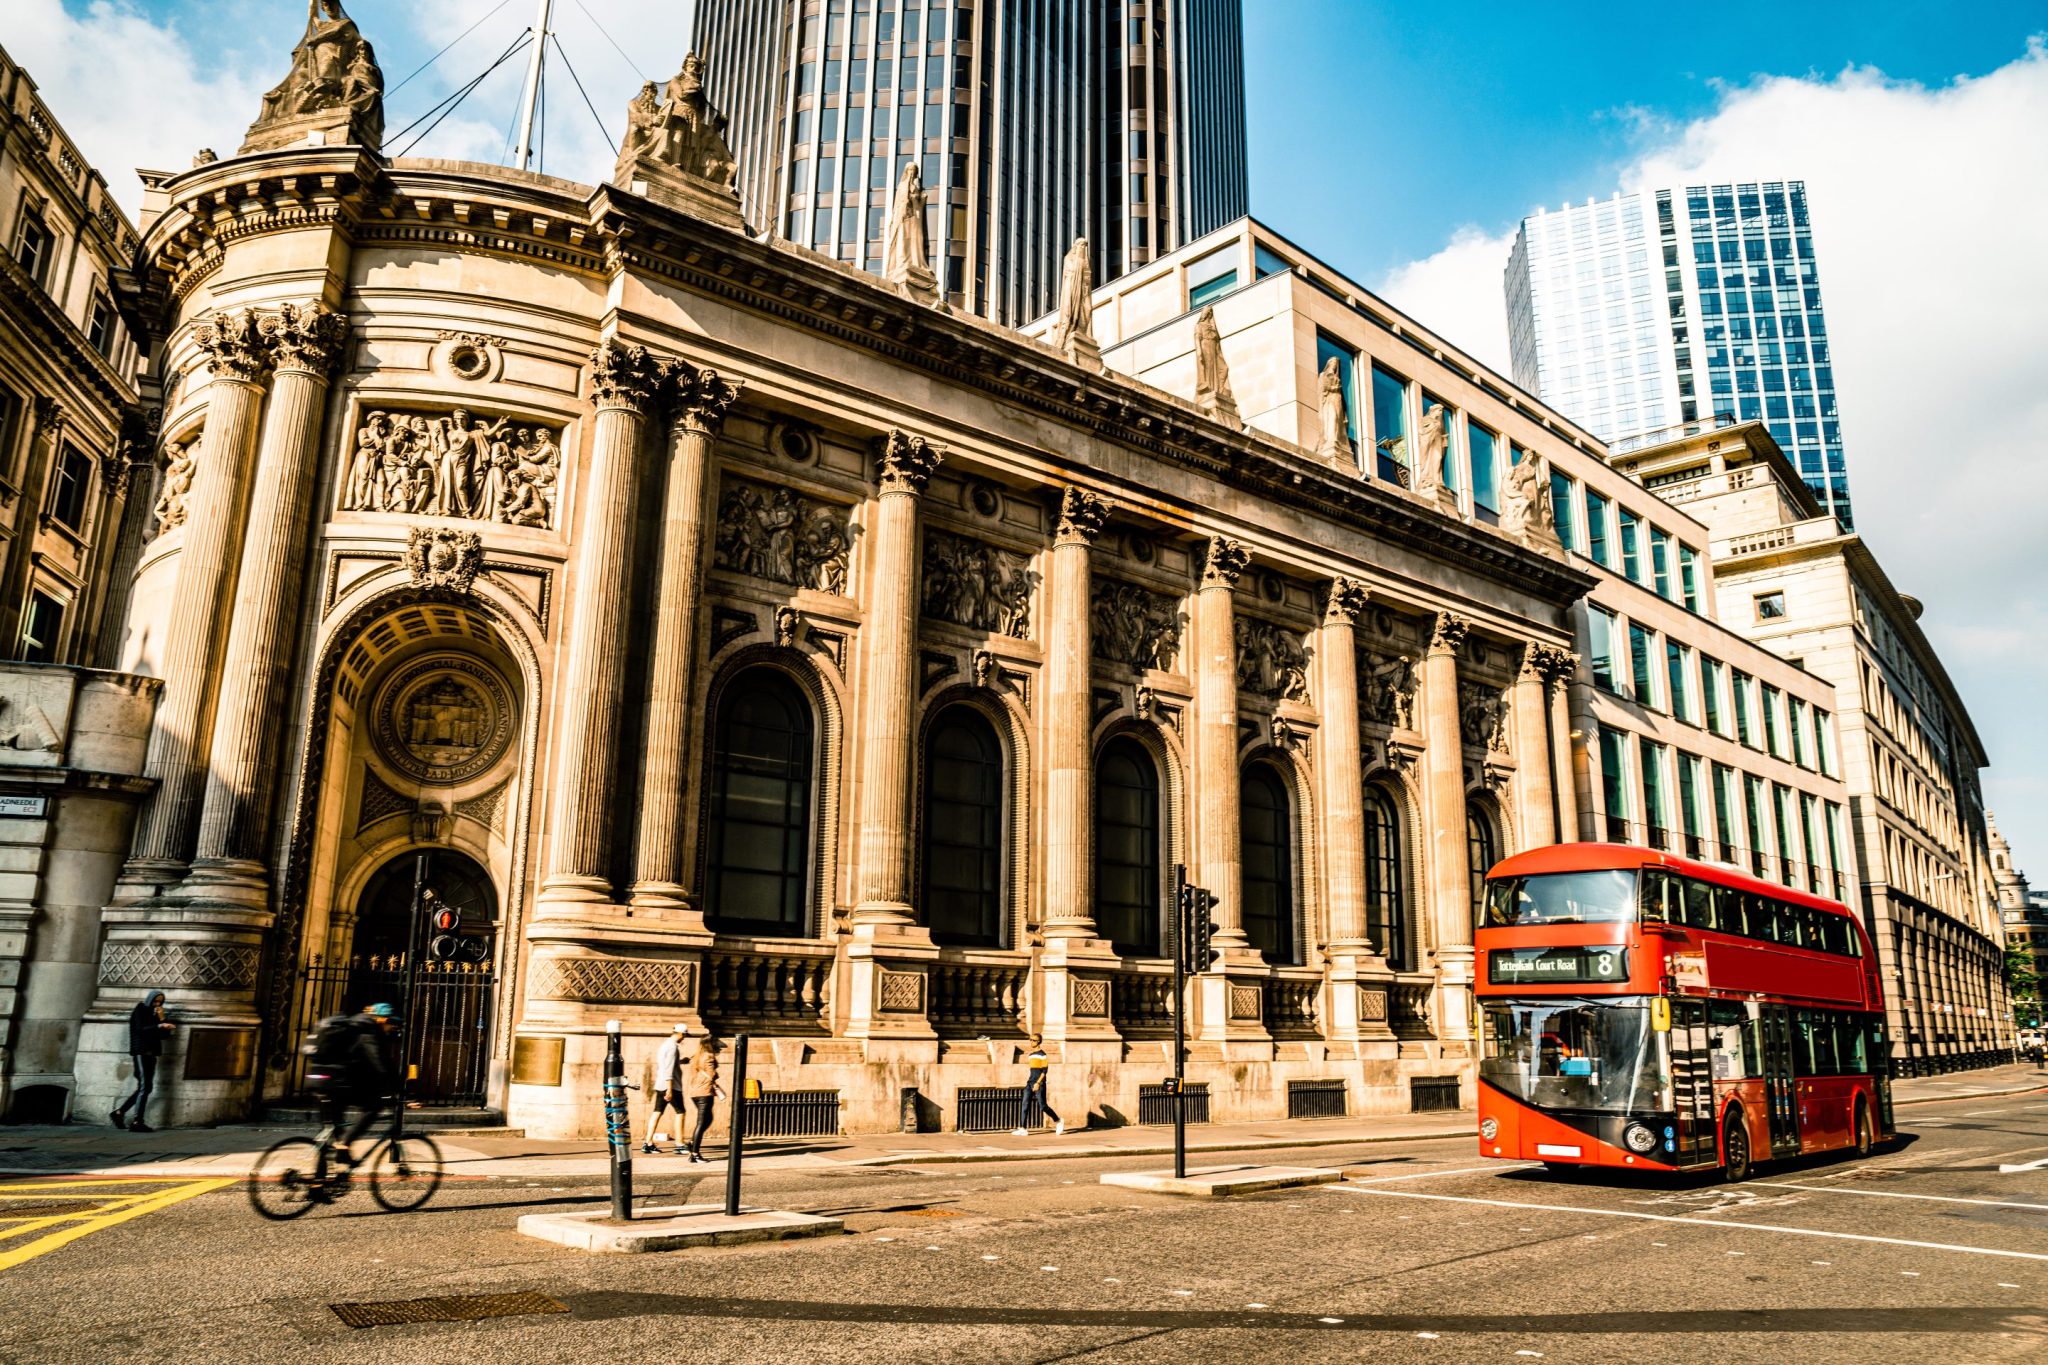
London, 1832. In a modest room on Lombard Street, clerks from thirty-one competing banks gather each afternoon. By 5 p.m., they begin the final settlement process. They are not there to negotiate individual transactions; that would be impossibly slow. They are participating in something revolutionary: the London Bankers’ Clearing House.
The technical challenge had already been solved. Banks understood double-entry bookkeeping. They could track debits and credits. They knew how to calculate a balance. The real problem was architectural: How do you enable daily transactions between competitors who fundamentally don’t trust each other? How do you create binding agreements when no single authority has enforcement power over all parties?